Search This Blog

Wednesday, 28 May 2014

Southampton performs well in the league tables, but don't be fooled by averages ( you can have your head in the oven and feet in the freezer - on average your temperature is OK but you are dead! )


The towns that offer the best buy-to-let returns

Rental returns on buy-to-let are biggest in regional centres like Southampton, Manchester and Nottingham – where one in four homes are now privately rented

Buy-to-let property management
Expert management: insured landlords can receive free business legal advice from Direct Line's helpline Photo: (c) Nick Free
Property investors are looking way beyond London and identifying regions where yields are almost three times as high as in the capital. Cities offering the greatest yields – rental income measured against the property's cost – include Southampton, Blackpool, Nottingham and Hull.
The latest data on buy-to-let returns, from lender HSBC, also shows the proportion of property in each area already owned by landlords. And in many of the top-yielding areas private landlords already own one in four properties, or more.
Southampton, with rental yields of 8.73pc, currently tops the list for rental returns. Manchester, Nottingham, Blackpool and Hull complete the top five locations with the best rental yield at 7.98pc, 7.67pc, 7.63pc and 7.47pc respectively. In all of these areas, except Hull, private landlords already own one in five properties, or more.
These areas also offer the characteristics that make for excellent buy-to-let investment, the experts say: relatively low house prices coupled with strong demand for rental property from large student and young professional populations.
RankLocation Housing privately rented (%) Average house price Average monthly rent Gross rental yield (%) 
1 Southampton23.42 £143,011 £1,040 8.73 
2 Manchester 26.85 £104,244 £693 7.98 
3 Nottingham 21.64 £86,000 £550 7.67 
4 Blackpool 24.16 £77,899 £495 7.63 
5 Kingston upon Hull 19.02 £68,243 £425 7.47 
6 Coventry 19.02 £110,029 £650 7.09 
7 Oxford 26.11 £254,514 £1,489 7.02 
8 Portsmouth 22.28 £146,709 £795 6.50 
9 Liverpool 21.75 £91,175 £494 6.50 
10 Cambridge 23.91 £185,414 £1,001 6.48 
The lowest yields were registered in areas such as London where recent price rises have been large and rapid, outpacing the growth in rents.
In London in particular, there is a higher proportion of rental property than elsewhere, with 38pc of property in Westminster, for example, being privately rented.
Worst 10 buy-to-let areas by rental yields
Location Housing privately rented (%) Average house price 
Average monthly rent
Gross rental yield (%) 
Kensington and Chelsea 33.97 £1,236,605 £2,968 2.88 
Thanet 21.96 £189,362 £524 3.32 
Hastings 27.19 £184,787 £520 3.38 
Haringey 30.33 £425,541 £1,200 3.38 
Westminster 37.56 £890,272 £2,578 3.47 
Hammersmith and Fulham 30.05 £685,797 £2,004 3.51 
Richmond upon Thames 20.55 £540,379 £1,699 3.77 
Camden 30.46 £715,831 £2,383 3.99 
Ipswich 18.75 £158,925 £546 4.12 
Lincoln 19.36 £124,789 £433 4.16 
Peter Dockar, head of mortgages at HSBC said: “House prices in the top-yielding locations – while still out of reach among many first time buyers – are relatively affordable for landlords investing in property and the demand from young professionals has pushed up rents and driven up the returns.
“London is often seen as the haven of property investment with many believing the streets are paved with gold. However, while the highest rents in the country are an attractive draw for landlords, high house prices in the capital squeeze yields and limit the returns available. As a result, returns can often be far more attractive in other areas so it certainly pays for landlords to do their research.”
HSBC's report draws on official data from the Office for National Statistics and Land Registry with rental data coming Home.co.uk.

http://www.telegraph.co.uk/finance/personalfinance/investing/buy-to-let/10859896/The-towns-that-offer-the-best-buy-to-let-returns.html

Tuesday, 27 May 2014

Why Southampton landlords should use Belvoir Lettings


Southampton property of the week


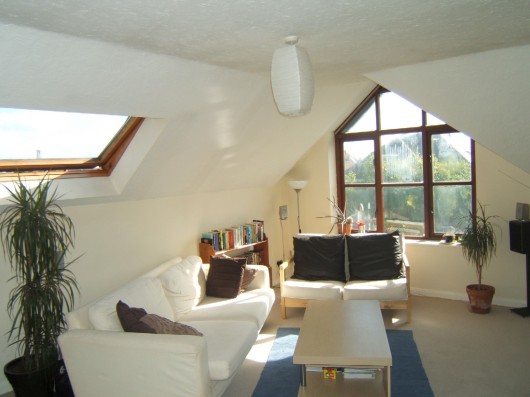
A really nice large and bright top floor 1 bed flat close to the central train station and the city centre with allocated parking. It is well positioned to service the General Hospital and universities and offers good access to the road network. It will rent for around £650 pcm and will produce a gross yield of 6.25% based on the asking price of £125k.

Southampton Landlords will interest rates of 3% become the new norm?


Interest rate of 3% could become new norm, suggests departing Bank of England man Charlie Bean

| 
Interest rates are likely to settle at around 3 per cent over the next three to five years, according to outgoing Bank of England deputy governor Charlie Bean.
His prediction that rates could hover at a lower level than during the pre-crash period came amid suggestions the move away from the historic-low 0.5 per cent base rate could begin sooner than expected.
Bean, the deputy governor responsible for monetary policy at the Bank, told BBC Radio 4's The World At One: 'The Bank rate averaged about 5 per cent in the decade or so before the crisis.

Rock bottom rates: Members of the Bank of England's monetary policy committee voted unanimously in favour of leaving interest rates on hold at 0.5 per cent earlier this month
'It's reasonable to think that, because of the headwinds that are still out there as well as some the global forces ... perhaps the level that we go to three or five years out might be a couple of percentage points below that.'
Members of the Bank's monetary policy committee voted unanimously in favour of leaving interest rates on hold at the same level since 2009 earlier this month.
 
But minutes of the meeting showed there was less agreement on the course for future rates. The first hike had been not expected until the second quarter of next year, or late in the first quarter.
Bean suggested it could start earlier with some 'baby steps'.
'There's a case for moving gradually because we won't be quite certain about the impact of tightening the Bank rate given everything that has happened to the economy,' he said.
'It might not operate in quite the same way as before the crisis. So that's an argument, if you like, for being a little bit cautious, moving in baby steps to avoid making mistakes.
'But of course if you want to pursue that strategy you need to start taking those baby steps a bit earlier, otherwise you end up being behind the curve.
'But there are arguments on the other side. In particular, one of the risks about moving too early is that you potentially forgo some activity that you might otherwise have had.
'One of the key issues for us will be whether we see some recovery in productivity which has been unusually subdued in recent years.
'It may be that if we nip the recovery too early we won't see that productivity rebound.'


Read more: http://www.thisismoney.co.uk/money/news/article-2638823/Interest-rate-3-new-norm-suggests-Bank-Englands-Charlie-Bean.html#ixzz32w5o53L5
Follow us: @MailOnline on Twitter | DailyMail on Facebook


http://www.thisismoney.co.uk/money/news/article-2638823/Interest-rate-3-new-norm-suggests-Bank-Englands-Charlie-Bean.html

Friday, 23 May 2014

Southampton Landlords it's all about quality tenant selection

Blackpool “tenant from hell”


Friday 23rd May 2014
A Blackpool landlord has taken his tale of tenants from hell to the local newspaper.
Sean Feeney rented out a property in Westmorland Avenue, Blackpool, to a mother and her three children. However he told the Blackpool Gazette he believes many more people could have been staying there.
Feeney faced a £2,000 cleaning bill when the family moved out after finding the property strewn with rubbish, dirt and graffiti.
Other Blackpool landlords have reported similar stories of being left to pick up repair bills stretching into thousands of pounds.
Feeney told the Gazette: “I spent £5,000 before re-renting it and they have vandalised it and left it in a sorry state, but the council have given these people a brand new council flat.
“The whole house is pretty much ruined. It will have to be gutted, and the last time this happened it cost £1,000 to take everything to the tip. I don’t know how people can treat a property like this then get a new one.
“The council should have had a look at my property, then told them they weren’t entitled to another one. I will easily have to spend another four or five thousand pounds on it. I don’t know how the carpet has got into that state – it looks like they have had cattle in there.”

Meet the team at Belvoir Lettings Southampton and learn how they go about their business


Great video showing how a professional letting agent goes about their business with a great culture and exceptional customer care

Monday, 12 May 2014

Earlier rate rise may be needed, warns CBI


Interest rates may need to rise sooner than expected to offset the impact of the UK’s overheating housing market as the economy’s growth accelerates, business leaders have said


London house prices have risen 25pc on their 2008 high, fueling speculation of a bubble. While housing transactions are currently running at 30pc below their 2006 peak and, nationwide, prices remain around 2pc down on 2006, the market is picking up pace. Property prices are set to increase by 8.2pc this year and 5.1pc in 2015.
According to the Confederation of British Industry (CBI), this could force the Bank of England to raise interest rates in the first three months of next year, before the general election, as opposed to the third quarter previously forecast. This has been echoed by economists, who claim that Bank governor Mark Carney will confirm interest rises on Wednesday, when the bank lifts its growth forecasts as part of its scheduled inflation report.
The CBI upgraded its GDP predictions from 2.6pc to 3pc for 2014 in its growth forecast, released today. Next year, the economy will expand by 2.7pc, rather than the 2.5pc previously forecast, it added.
http://www.telegraph.co.uk/finance/economics/10823094/Earlier-rate-rise-may-be-needed-warns-CBI.html