Search This Blog

Monday, 21 March 2016

Demands on the Private Rented Sector are greater than ever


RLA Policy Director David Smith has given evidence to the House of Lords Economic Affairs Committee as part of its inquiry into the UK housing market.
Dr Smith told Peers that it is the lack of housing, not the number of buy-to-let landlords that is the major crisis facing the UK – and said that the demands on the Private Rented Sector are greater than ever before.
He said: “Unless we address supply radically, there will be no significant change in housing cost. Simply shifting the dynamics so that it is more attractive to owner-occupiers than it is to private landlords does not increase supply; it just moves property around a merry-go-round. We must increase supply. Everything else, to some extent, is a red herring.”
Dr Smith also promoted the RLA’s call to local authorities to free up small plots of land that could be redeveloped as housing, after 46% per cent of RLA members responding to a survey said that they would be interested in helping to fund developments of fewer than 10 units.
He said: “At the moment, there is no pressure on local authorities to release small plots. We asked the two proposed candidates for the new (London) mayor, whoever is finally elected, to look at using their planning powers to reconsider that.
“Currently, the mayoralty’s planning interests focus more on building large institutional structures or large buildings that are sold to private sector landlords abroad. We have asked the mayor to rethink his planning powers to look at smaller plots and to encourage or compel local authorities to make them available.”
He also commented on the new changes to Stamp Duty Land Tax, calling for tax relief for those investing in new build. He said: “We would like to see a change to the Stamp Duty Land Tax to give landlords a discount on the 3% increase when they have done something that brings new-build property on to the market.
“Where they have invested money in new-build property, thereby increasing the overall supply, hopefully, we think that they should be relieved from the 3% uplift that will apply to Stamp Duty Land Tax.”

Monday, 14 March 2016

Property buying ‘frenzy’ spreads across the country


A property buying spree recorded in the East of England last month has now spread across the rest of the UK. The latest report from Home.co.uk calculates that average house prices will rise by a further 0.9% this month, bringing the annual growth figure up to 7.9%. 
The property website says that fierce competition among buyers in the early spring period has driven down typical time on the market figures in many parts of the country, with the East and South East regions of England registering the shortest marketing times recorded since the summer of 2007.
According to Home, the typical time on the market across England and Wales is now just 102 days, 17 fewer than in March 2015.Over the last month, the longest marketing times were recorded in the North and Wales as supply remains 'relatively buoyant' and prices remain stable.

Home says, however, that the total stock of available property remains very low and that the number of properties currently entering the market is 4% lower than this time last year. It reports that the West Midlands has been hit the hardest, with stock levels 12% lower last month when compared with February 2015.
Agents' stock also dropped by 8% last month in the South West when compared with the same period last year.
Doug Shephard, Home.co.uk director, says the ‘buy-to-let stampede’ before April’s 3% stamp duty surcharge has doubled the effect of the annual spring boost in property market activity. 
“This investment frenzy is providing fierce competition for first- and next-time buyers who are probably best advised to stay out of the fray until the dust settles,” he says.
“We expect that prices there will reach their affordability limits later this year and a similar market dynamic will take hold in the West Midlands, the South West and the East Midlands towards the end of the year, together with significant price growth in 2017.”

Home expects that post April the market will ‘pause for breath’ but that the underlying fundamental of cheap borrowing and tight supply will remain overall.

Tuesday, 8 March 2016

Lovely 1 bed maisonette yields 6%, yours for £135k

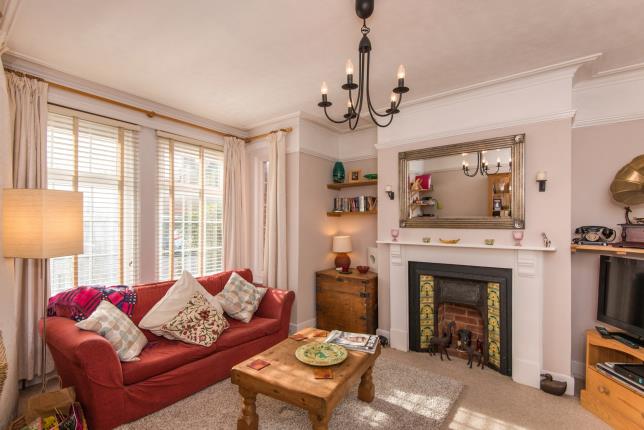
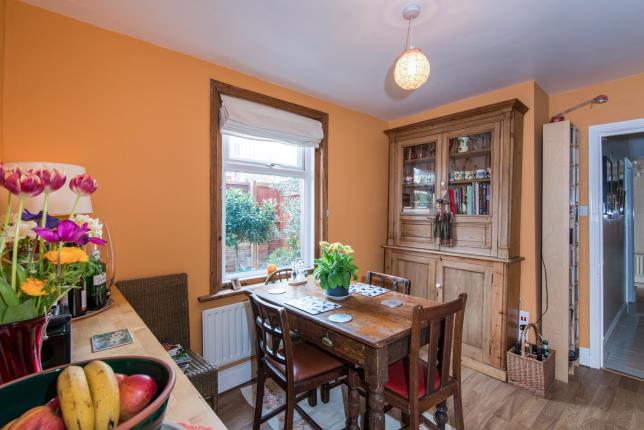
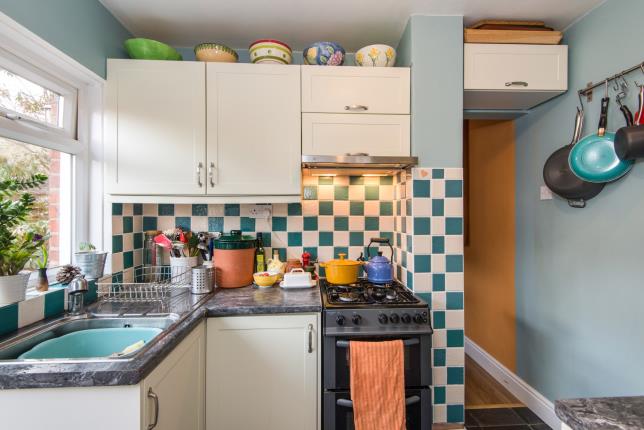
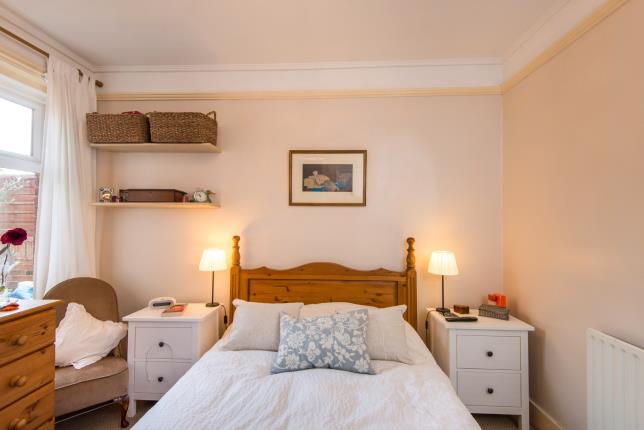
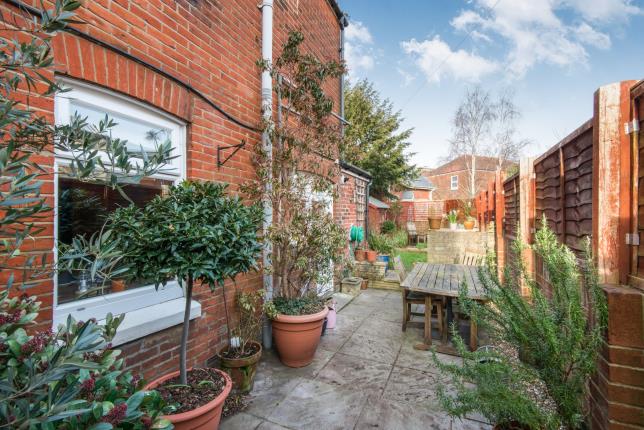
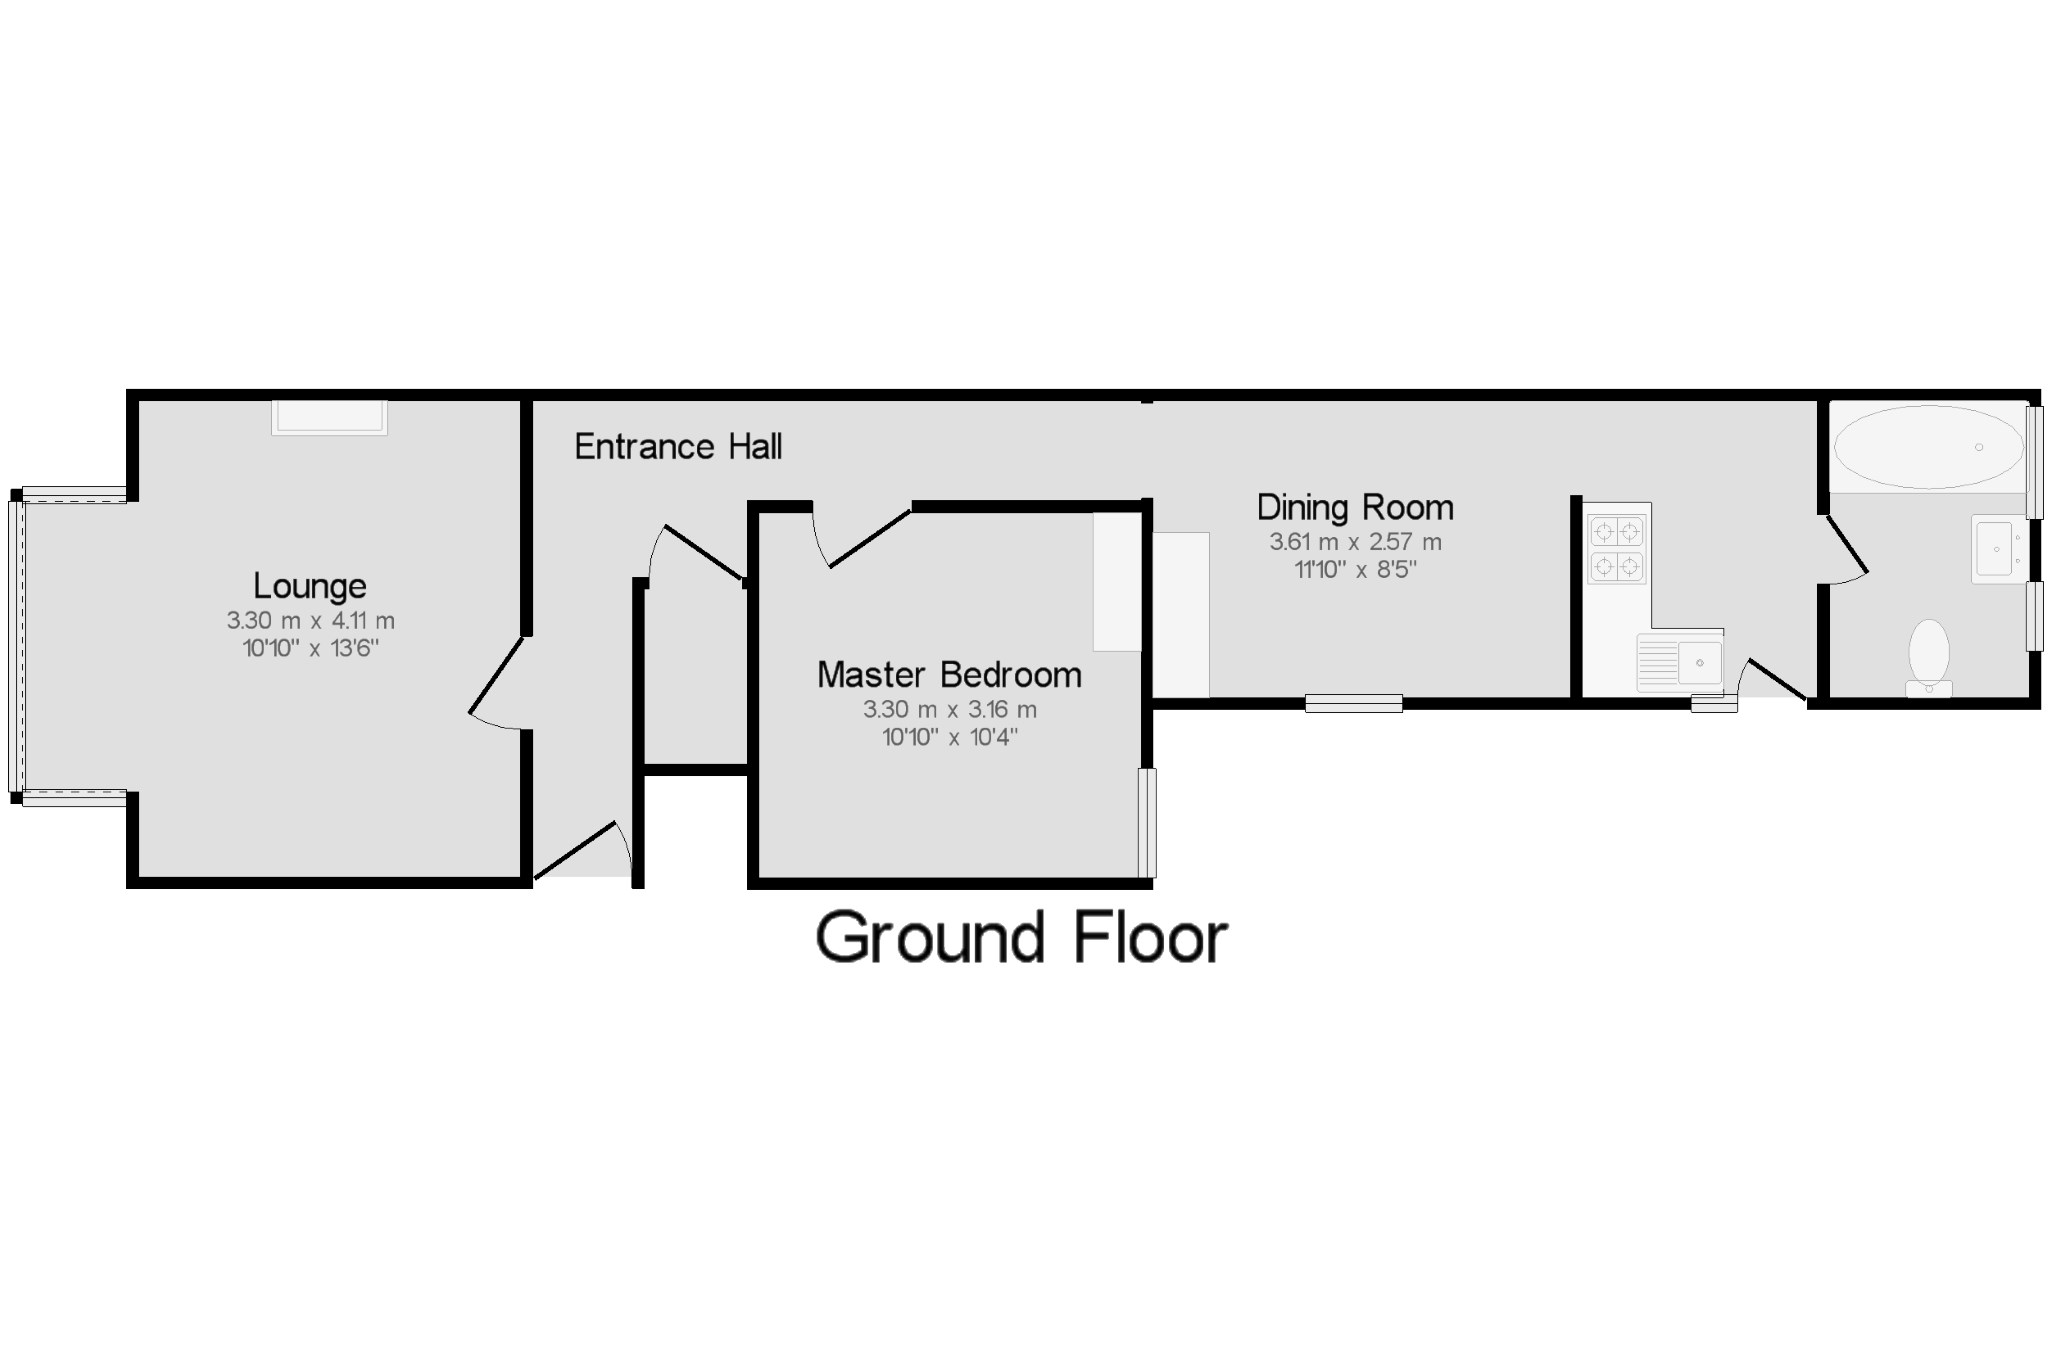
This is a great ground floor 1 bed maisonette in a good location between Hill Lane and Shirley Rd. You have the use of the back garden and while there is no off road parking there is sufficient parking by permit on street. The unit will let well at £675 pcm to a professional tenant. Gross yield is good at 6% based on asking price of £135k, but I would hurry it wont be around for long!! full details can be found at http://www.zoopla.co.uk/for-sale/details/39681586#cepwX7dLRF2mIMyb.97

Monday, 7 March 2016

Renters must earn over national average to be able to buy


The gap between average incomes and the pay of tenants who want to buy their first property has reached a post-recession high.
Analysis of data from the Office of National Statistics and the Council for Mortgage Lenders shows that the average income to support a first time buyer mortgage is £38,977 - that’s £11,332 higher than the average UK salary of £27,645.  
This is the widest gap there has been since the recession, signalling how access to home-ownership in the UK has become increasingly exclusive – and indicating why the lettings sector is likely to grow in the future.
The income gap has grown considerably in recent years in response to tighter lending criteria and rising house prices, making it harder to get onto the property ladder and blocking many from home-ownership without support from a partner, family member or government scheme.
In comparison, the gap between the average salary to support a first time buyer mortgage and the average UK salary was just £3,170 in 2000 and £7,505 in 2011.

In London the average salary supporting first time buyer loans is almost £58,500 or 65% more than the UK average. 
Compared with regional salary growth of just 1.3%, London has seen first time buyer incomes rise by 19.4%.
This means that the first time buyer to average income gap in London equates to £23,142, more than double the UK average of £11,332. It is also 3.9 times more than in Yorkshire, where first time buyer to average income has the smallest gap. This again highlights the massive difference between the haves and have-nots.

The research was conducted for mortgage insurer Genworth.

House prices increase by 9.7% in the year to February 2016


Last week we saw the publication of the latest Halifax House Price Index. As usual it sheds some interesting light on the housing market. Its main findings are:


  • House prices in the 3 months to February 2016 were 9.7% higher then in the same 3 months a year earlier.
  • House prices in the last 3 months were 3% higher then in the preceding three months.
  • House prices decreased by 1.4% between January and February. This offset much of January's 1.7% rise.
  • Increase in areas where homes have risen more in value than owners total earnings.
  • Home sales remain on an upward trend - 9.3% higher then 12 months ago.
  • Mortgage approval higher. 5% increase in approvals between December and January, now stand at 74,600 approvals, which is the highest level since January 2014.
  • House supply remains low but showing signs of slight improvement.
  • Number of new homes built increased by 7% between Q3 and Q4 2015. Overall completions were 20% higher in 2015 than 2014 and are at their highest annual level since 2008.

Will changes to the immigration bill protect Southampton's landlords?


Landlords will no longer be immediately criminalised for failing to pick up illegal tenants, according to the Residential Landlords Association (RLA).
The landlord body has been campaigning for changes to the government's Right To Rent legislation and says the government has now agreed to changes to the immigration bill which will provide protection for landlords who take reasonable steps in an appropriate time frame to terminate tenancies of tenants in the country illegally. 
 
Previously under the bill, landlords would face immediate criminal sanctions upon discovery that they failed to ensure their tenants had the right to rent property in the UK.
 
The Government has also agreed to look at changes to regulations to enable landlords to provide information such as tenancy deposit schemes to tenants via email instead of in paper form as currently is required.

Speaking for landlords, the Residential Landlords Association (RLA) has campaigned for both changes and very much welcomes the Government’s proposals.
 
RLA chairman Alan Ward said: “The RLA warmly welcomes the Government’s pragmatic changes to its right to rent scheme that will provide protection for good landlords from the unintended consequences of the policy.
 
“It is also welcome that the Government is willing to look at how electronic information can be better used to provide tenants with the legal information they require. In the 21st Century it is ridiculous that landlords are expected to print so much paper when it can be provided at the simple click of the button.”

Are Southampton retirees raiding their pensions for buy 2 let?


Downsizing has fallen out of favour with older homeowners, with more and more purchasing their dream retirement property and then renting it out until they are ready to move in.
According to research released today by Prudential, 20 per cent of over-55s would consider making a buy to let investment with the intention of living in it themselves one day, while a third (32 per cent) of those who already have a buy to let property are thinking about moving into it sometime in the future.
However, when asked how they intended to fund their purchase, around half (52 per cent) said they would take a lump sum from their pension.
"The advent of older people opting to buy-to-let-to-retire is an interesting development, and in a post-pension freedoms world its appeal is understandable," said Stan Russell, a retirement expert at Prudential. "However, there are a number of risks involved for anyone looking to take money from their pension savings, irrespective of the reasons."
Since the pension freedoms came into force last April, those aged 55 or over are able to withdraw money from their pensions pot without first purchasing an annuity.
Russell continued: "The simplest approach for most people looking to give themselves choices and secure their ideal home when they retire is to save as much as possible into a pension as early as possible in their working life."
From 1 April this year, an additional three per cent will be charged on stamp duty land tax (SDLT) for those purchasing a buy to let property. The new charge was announced in last November's Autumn Statement.

Government launched a consultation into the new higher rate of SDLT in December last year and is currently analysing the feedback it received.